

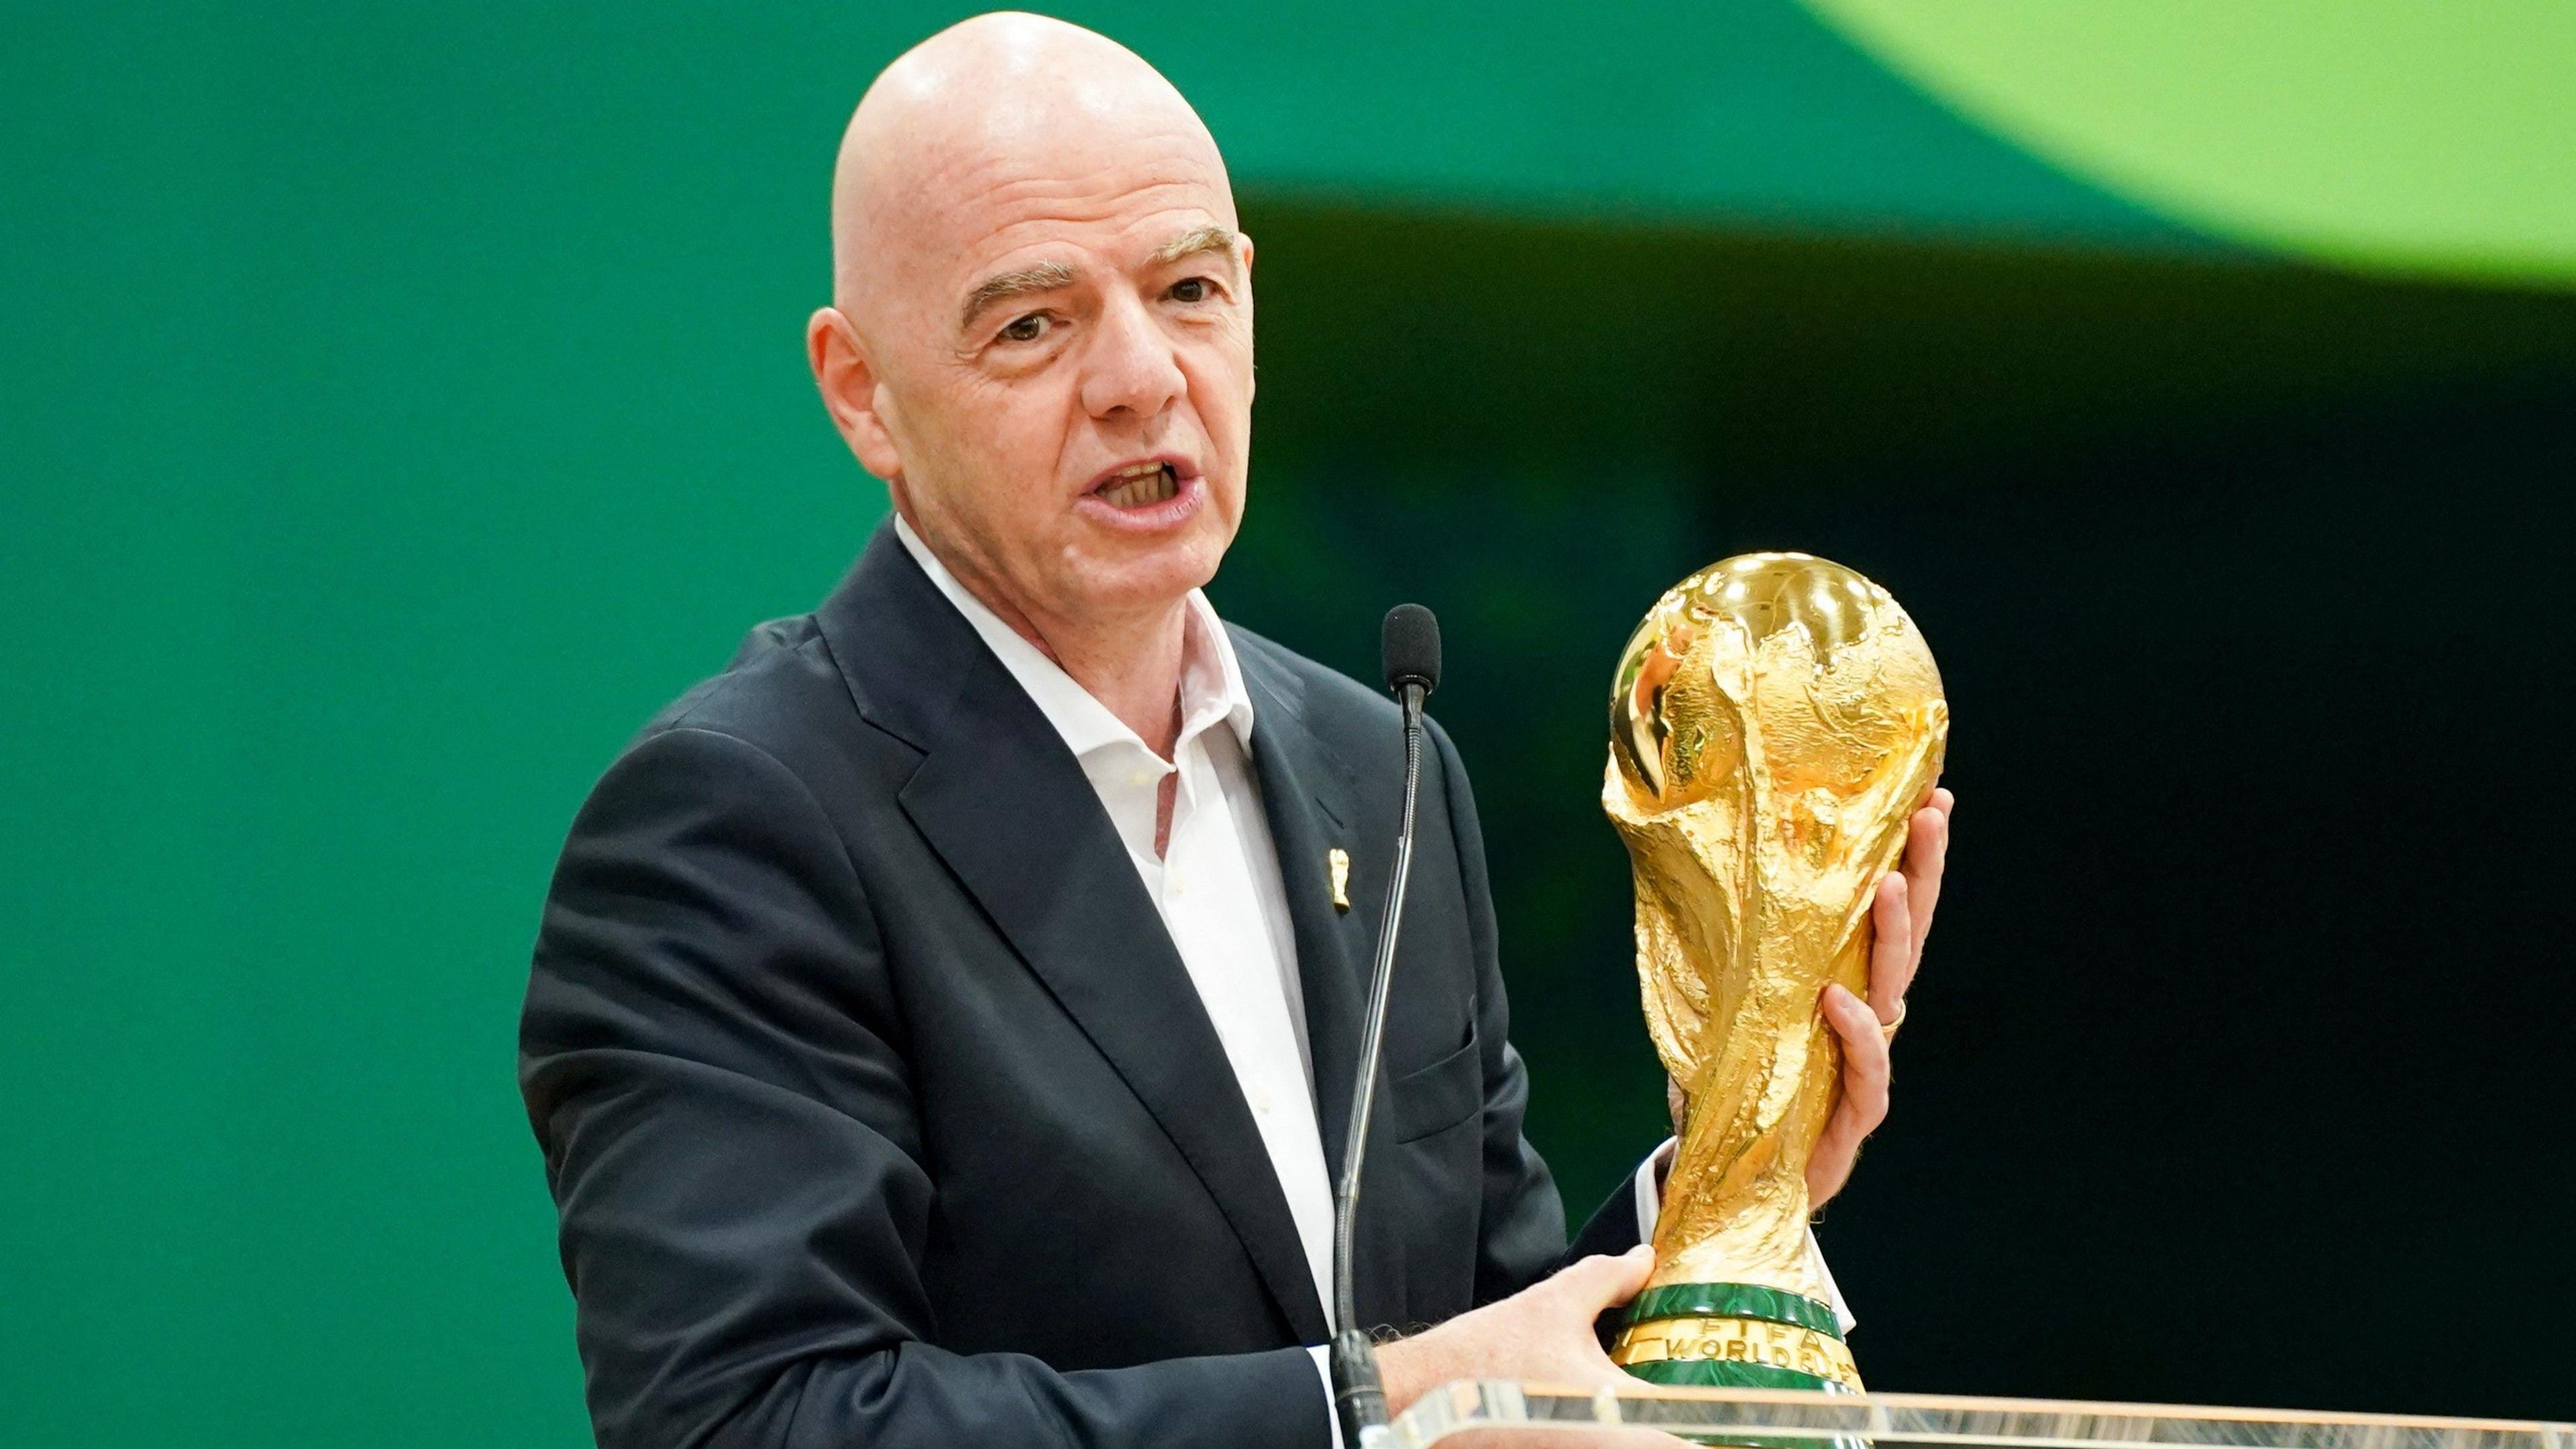
Why did Gianni Infantino’s plan to sell a stake in the World Cup fail? Which company in Europe is the largest owner of forests? These two questions are related - and are in turn connected to a case for much wider public ownership of countries.
Infantino’s plan failed because, despite being the nominal boss of Fifa, he did not actually have the power to deliver a meaningful World Cup to outside investors. In threatening to withdraw from the competition, European national football associations were able to prevent a worthwhile event: a World Cup without Spain, France, Germany or England would not be much of a spectacle.
This is an example of a longstanding issue in economics. It’s the so-called hold-up problem. It occurs whenever somebody can hold up production by withdrawing their supplies in order to get their own way. European FAs threat to not participate in a World Cup meant that Infantino didn’t have the power he thought he had.
Companies face this problem all the time. Suppliers of essential parts or labour can threaten to hold up production by withdrawing their efforts and so extract extra income for themselves.
Often, a solution to this is simply to write contracts compelling such parties to provide goods and services at a set price. But this isn’t always possible. Contracts often cannot fully foresee all contingencies or fully specify the precise quality to be supplied (footballers can’t be forced by contract to play well) and even if they can it takes millions of pounds and lots of management time to enforce them. This, I suspect, was Infantino’s problem; he didn’t have a contract compelling national associations to compete in a changed tournament*.
Where contracts are incomplete or unenforceable except at high cost, companies have another solution - ownership. If they buy the supplier they can replace a contractual relationship with a command-and-control one. That, said Ronald Coase (pdf), is why companies exist at all: sometimes market contracting is so expensive.
This is why the same companies own oil drillers as well as refineries or why Tesco has a large fleet of lorries rather than rely on subcontractors. And it answers our second question. Ingka holdings, who own many Ikea shops, is also a huge owner of forest land - 495,000 hectares. Such ownership gives the world’s largest user of timber a guaranteed supply, thereby reducing the hold-up problem. All these are examples of what Oliver Hart and John Moore wrote in a classic paper (pdf): “assets that are highly complementary should be owned together.”
But by whom? It doesn’t matter whether the oil driller owns the refinery or vice versa. But in other cases it does matter. This is because it’s not just owners of physical assets that can hold up production. So too can owners of human capital. The textbook example (pdf) is that of Saatchi & Saatchi. In 1994 shareholders wanted to dismiss Maurice Saatchi as chairman, resenting his high pay and failure to cut costs. Saatchi walked away to form a new company, taking many employees and clients with him. Saatchi and Saatchi went into decline. Those shareholders made the same mistake as Infantino. They thought formal control meant real control. It didn’t. Power lay not with them but with Saatchi.
In these cases the solution is for powerful agents to own the company. As Hart and Moore say, “If an agent is indispensable to an asset, then he should own it.” And again, this is what what often happens**. Business founders own their companies because they are indispensable, say because they have especial knowledge of the production process or have clients personally loyal to them. And many human capital-intensive companies such as law, accountancy or vets practices are owned by partners because if they were mere employees they might do a Saatchi and leave, taking clients, knowhow and colleagues with them.
Powerful agents shouldn’t own companies merely because they could hold up production if they didn’t. They should also do so for a related reason. We want assets to be controlled by those best able to mazimize their value. Because essential people are best able to do this, it is they who should be in control. To incentivize them they should be, in the jargon, the residual claimant - the ones who get what’s left after contracting parties (banks, bond-holders, employees, suppliers etc) have got what the contract specifies. If the company does well, the residual claimant gets big profits, and if it does badly they lose. Incentives should align with the power to make the most difference. And often they are, as when partners or business founders own the company.
The hold-up problem, and its close cousin the residual claimant theory, therefore helps explain lots of what we see about how assets are owned.
But, but, but. There are many issues here. I’ll name just a few.
One is that the residual claimant sometimes isn’t the agent that can maximize the value of the company. External shareholders are residual claimants in that they get what’s left of the company after other creditors have their pickings. But they can do a poor job of maximizing the value of the company because they do not exercise adequate control of management. This is one reason why we had a financial crisis in 2008: shareholders didn’t stop banks from holding bad assets. It’s not accident that building societies which had thrived for decades under mutual ownership collapsed after only a few years with external shareholders.
This problem is an old one. Back in 1989 Michael Jensen wrote:
The idea that outside directors with little or no equity stake in the company could effectively monitor and discipline managers who selected them has proven hollow at best...Institutional investors are remarkably powerless.
The publicly quoted company, he wrote, “has outlived its usefulness in many sectors.” And he was right. Rene Stulz and Kathleen Kahle have documented how the number of companies listed on US stock markets has declined markedly since the 70s with the result that those markets, dominated by a few colossal companies, are less representative (pdf) of the US economy than ever before.
Whilst Jensen’s diagnosis was excellent, however, his prescription has been less so. He wanted managers to have stronger incentives to maximize the value of companies and so favoured things like leveraged buy-outs that would give bosses bigger stakes. We know now, however, that these incentives can causes bosses to chase short-term rewards (pdf) to the detriment of the longer-term health of the company, and can crowd out erstwhile non-financial motivations such as the desire to be a good steward.
Of course, this wouldn’t matter much if the value of a company were merely a private matter between consenting adults. But in important cases it is not, because there are externalities. We saw one in the financial crisis, when the collapse of banks hurt not just shareholders but us all; not only did it cause a recession but it also exacerbated long-term economic stagnation which itself contributed to Brexit. Climate change is another example: the social value of (say) oil companies comprises not just the oil they produce but also the emissions that cause climate change. As Colin Meyer has written (pdf):
Shareholders are not...by any means the only party exposed to the misfortunes of corporations and the more...we strengthen the rights and powers of shareholders, the more we threaten the interests of others.
In a sense all of us are residual claimants upon companies that spew out unpriced or underpriced externalities, be they the risk pollution of banks or the environmental pollution of water companies or the existential danger of catastrophic climate change. In principle, governments could internalize these externalities by taxes or regulation - in effect, pseudo-contracts that shift residual claimancy back onto their owners or managers. In practice, this hasn’t happened. Which opens up a possibility: if we are residual claimants upon banks and other polluters, shouldn’t we have an ownership stake as other ordinary residual claimants do?
Something else reinforces this question. Let’s go back to Hart and Moore’s claim that “if an agent is indispensable to an asset, then he should own it.” In most cases, each individual worker is not indispensable. But collectively, workers are indeed indispensable; if they were to all go on strike, production would cease. The hold-up problem re-emerges. As Hart and Moore say:
What happens if a whole group of agents are indispensable to an asset? In this case, one (or more) of the group should always be given control over the asset.
This is close to what Marx thought. He thought that the working class would grow so powerful that it could eventually act like a single agent, causing a hold-up problem for capital as a whole and so demonstrating its indispensability and hence claim to ownership:
The advance of industry, whose involuntary promoter is the bourgeoisie, replaces the isolation of the labourers, due to competition, by the revolutionary combination, due to association. The development of Modern Industry, therefore, cuts from under its feet the very foundation on which the bourgeoisie produces and appropriates products. What the bourgeoisie therefore produces, above all, are its own grave-diggers.
This didn’t happen because of the collective action problem. It’s difficult to get people to act as one and so the working class has not been able to demonstrate its collective indispensability. The economic logic for collective ownership which Marx thought would emerge has not therefore done so. And so capitalism, in some form, has survived. It is insufficiently appreciated that the economics of asset ownership has wider applications than generally realized.
* In this sense, the tragedy of Infantino is similar to that of Shakespeare’s most sympathetic tragic hero, Shylock. Just as Shylock failed to see that he needed a more complete contract than he had if he were to extract a pound of Antonio’s flesh, so Infantino didn’t realize that he needed a contract compelling national teams to play in a privatized tournament. Both are guilty of not appreciating Coase’s insight that contracts are often imperfect - though Shylock at least had the defence of having lived 300 years before Coase wrote.
** Such agents don’t always own the company if they can extract what they want by their strong bargaining position. This is why footballers don’t own football clubs, why bankers don’t own banks, and why powerful trades unions in the 60s and 70s rarely pushed for ownership stakes. There are however drawbacks to such non-ownership: larger football clubs are owned by reputation launderers and banks are vulnerable to crises.
Excellent infornative article that with the referenced links acts also as a good 'teach yourself real world economics' source.
A couple of anorak points.
One, was the trigger of building society demise financial liberalisation and access to wholesale funding markets rather than simple change of ownership arrangements, which was largely a consequece rather than a cause?
Two, was not the failure of working class collective action to be the 'grave digger of capitalism' a compex political economy phenomena, motivated, at least in part, by a realistion that simply transferring prodctivive enterprises to the grave did not accord with worker self interest. interacting with ameliorative public abd social policy interventions?
The question this raises for me is what role fifa actually plays with respect to football. They extract a lot of value but I’m not clear why this is the case and why the significant footballing nations actually participate in it. It’s not really like a company, more like a trade association